中文
 English
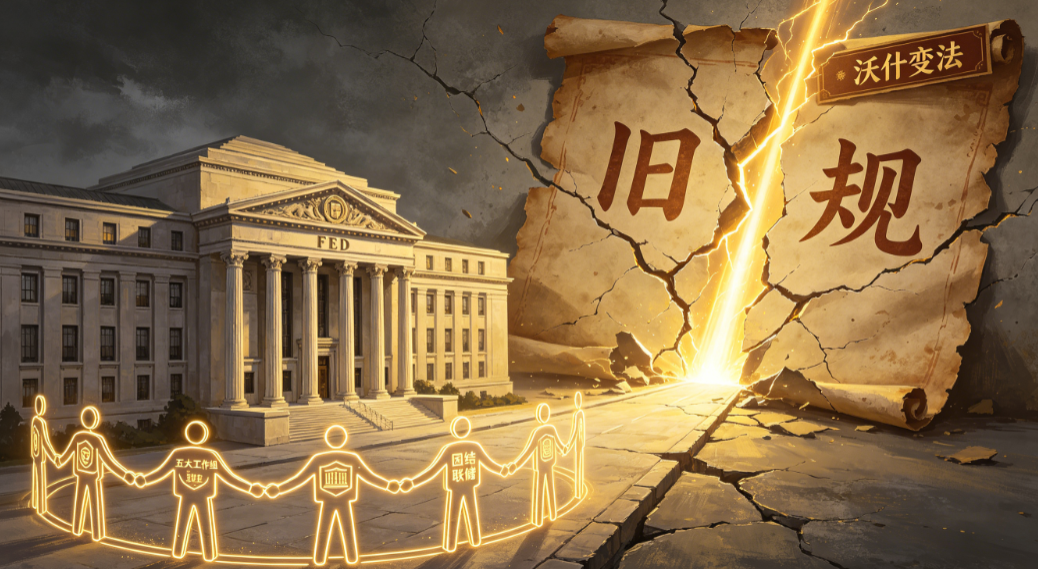
Warsh‘s “Soft Reform”: Fed Overhaul Starts with Debut
Keywords: Federal Reserve, Warsh, monetary policy, communication reform, balance sheet, inflation framework, dot plot, central bank
Introduction: A Debut Without Conflict, That’s Exactly What’s Worth Attention
By Wall Street standards, Warsh’s debut last week was almost “perfect.” No expected hawk-dove showdown, no open disagreement between chair and governors, and no dissenting votes. Instead, the new chair, who had once called for a “regime change” at the Fed while competing for the position, completed the transition from critic to manager with a unanimous rate decision.
But what’s really noteworthy is not just the meeting’s calm surface, but the reform signals beneath it. Warsh did not launch change aggressively; instead, he chose to embed reform within order and advance adjustment within consensus. He announced five task forces focusing on communication mechanisms, balance sheet, data use, productivity and employment, and inflation framework, meaning the Fed’s policy machine is entering a systematic overhaul.
1. From Confrontation to Integration: Warsh’s Political Acumen
Warsh’s transformation first shows in style moderation. He previously criticized the Fed sharply and directly, even using “loss of credibility” to frame problems. Now, he emphasizes efficiency, tradition, and teamwork. This change does not mean weakened reform will; rather, it shows he realizes that within a central bank system, truly effective reform often comes not from head-on collisions but through organizational procedures and institutional design.
Setting up task forces is a typical “advance by retreating” tactic. It reduces internal resistance and builds research and consensus for major adjustments. For outsiders, this is a gentle transition; for the Fed, it may be a deep institutional reconstruction.
2. Five Task Forces: Reform Is Not Tinkering
From content, the five task forces target the core of the Fed’s policy framework.
First, communication reform. For a long time, the Fed’s templated statements, verbose phrases, and “forward guidance” model have been criticized for information overload and signal deficiency. Warsh pushing statements back to simplicity means the central bank wants to reduce excessive market interference from “language management” and shift to more direct, transparent policy expressions.
Second, balance sheet policy. Since the financial crisis, the Fed’s balance sheet has continuously expanded, and central bank functions have extended. Warsh’s reservations about large-scale asset holdings reflect his desire to re-examine the boundaries of unconventional tools, avoiding long-term reliance on asset purchase mechanisms.
Third, data sources and analysis methods. The future economy will be more complex; AI, supply chain restructuring, and labor structure changes require central banks not to rely solely on traditional lagging indicators. Strengthening frontier data, quantitative models, and real-time monitoring may become an important basis for next-stage policy making.
Fourth, productivity and employment. This means the Fed is starting to pay more attention to the long-term impact of supply-side changes on inflation and employment, rather than simply using traditional demand management logic.
Fifth, inflation framework. The misjudgment of inflation in 2021-2022 exposed the limitations of the existing framework. Reflecting on the “transitory” mistake will clearly help the Fed redefine its inflation target, tolerance range, and reaction mechanism.
3. The Real Difficulty Is “How to Explain Clearly”
Although Warsh’s move is seen as the start of reform, the real challenge has just begun. One of the Fed’s strongest abilities is not tools but expectation management. If communication mechanisms change, the dot plot is weakened, and forward guidance fades, the first question markets face is: what will the Fed base its decisions on in the future?
This is also the key point former officials repeatedly emphasize. Central bank reform cannot only stress “what to change” but also clearly explain “why change” and “to what extent.” If there is no clear reaction function, markets easily interpret institutional updates as rising uncertainty, amplifying volatility and even undermining policy credibility.
In other words, for Warsh’s reform to succeed, the key is not how many changes he makes but whether he can establish a new policy language that markets can understand and anticipate. The most taboo thing for a modern central bank is not toughness but ambiguity.
Conclusion: Deep Restructuring Under a Gentle Facade
Overall, Warsh’s debut was not a routine rate-setting meeting but the starting point of a Fed reform narrative. He used a calm appearance to buy space for institutional progress, and wrapped structural adjustment ambitions in consensus language. This approach shows political acumen while implying the Fed will enter a deeper period of self-examination.
From communication to the balance sheet, from data dependence to inflation framework, the Fed is trying to break free from old paradigms and seek a policy system more suited to the new economic environment. However, the success of any change ultimately hinges on one thing: maintaining market trust in the central bank while reshaping institutions.
Warsh has taken the first step, and quite impressively. What follows will be the true test of his reform capability.